


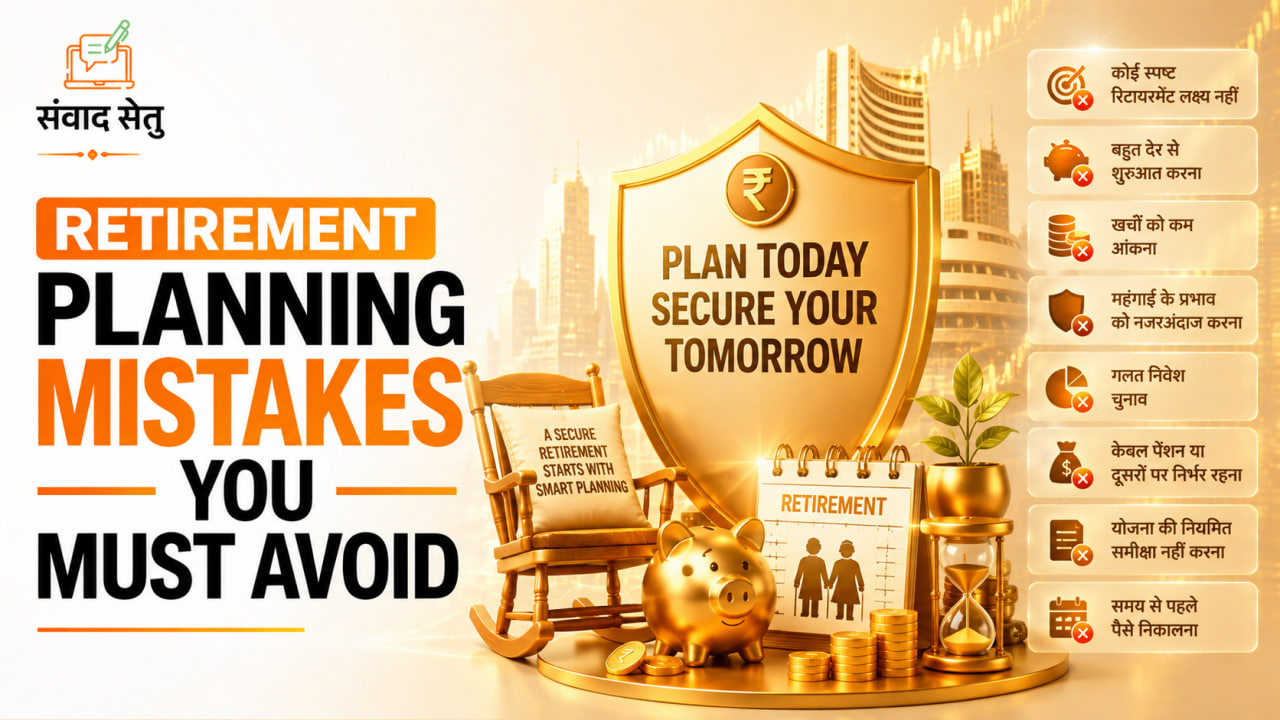
Common Mistakes to Avoid in Retirement Planning: Secure Your Future Before It's Too Late
Introduction
Retirement is not the end of earning—it's the beginning of living on what you've built over the years. Every working professional dreams of a financially independent retirement where they can spend time with family, travel, pursue hobbies, or simply enjoy peace of mind without worrying about money.
However, achieving this dream requires careful planning. Unfortunately, many individuals postpone retirement planning or make mistakes that significantly impact their financial security later in life. The good news is that most of these mistakes are avoidable with awareness and disciplined financial planning.
Let's explore the most common retirement planning mistakes and understand how you can avoid them.
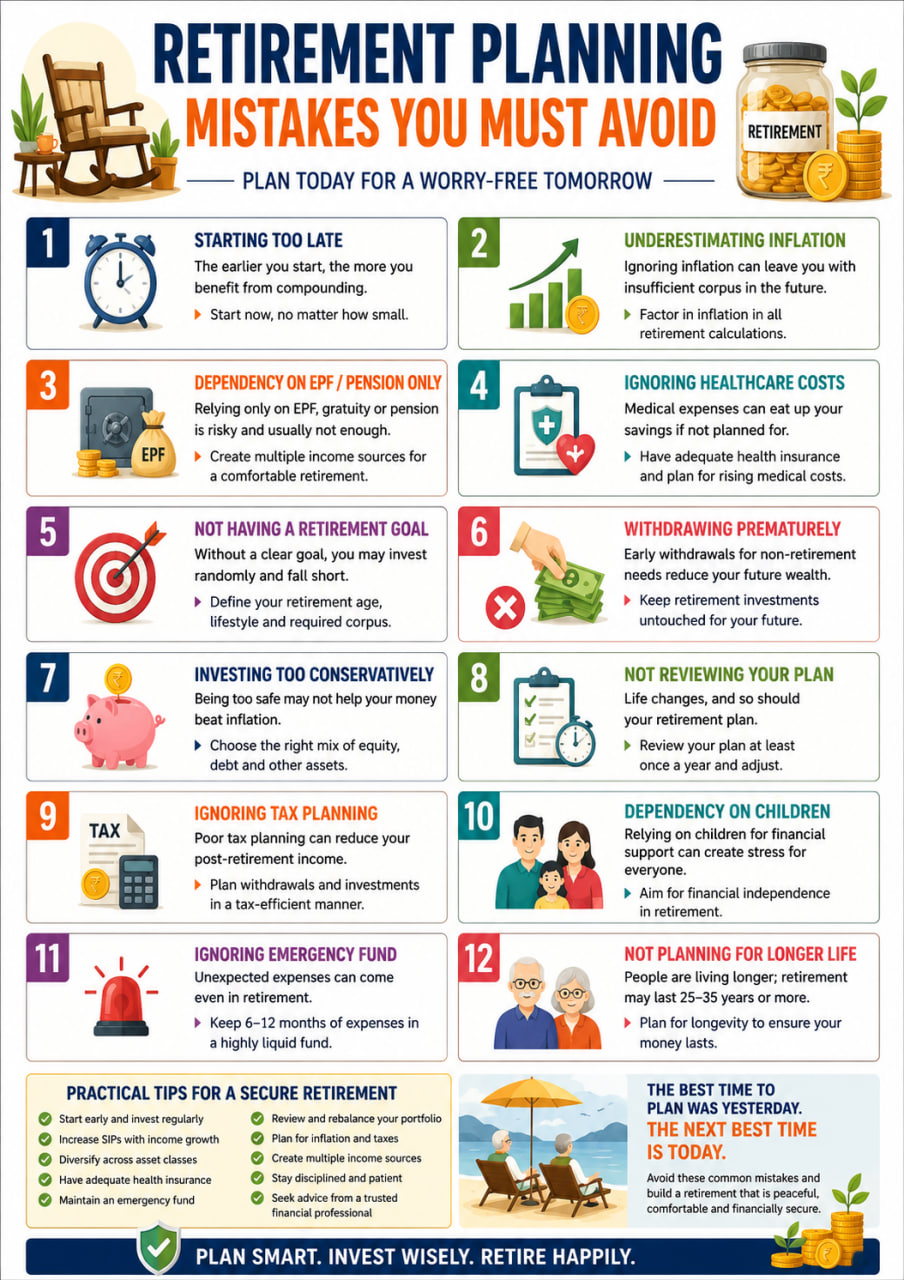
1. Starting Retirement Planning Too Late
The biggest mistake people make is assuming they have plenty of time.
Many individuals believe retirement planning should begin in their 40s or 50s. In reality, the earlier you start, the more you benefit from the power of compounding.
Example:
- Person A starts investing ₹10,000 per month at age 25.
- Person B starts investing ₹20,000 per month at age 35.
Despite investing twice as much monthly, Person B may still accumulate less retirement wealth because Person A had the advantage of time.
Lesson: Time is the greatest asset in retirement planning.
2. Underestimating Inflation
Today's expenses won't remain the same after 25 or 30 years.
A monthly household expense of ₹50,000 today may become ₹1.5 lakh or more by retirement, assuming inflation of around 6%.
Many people calculate retirement needs based on current expenses and ignore inflation, leading to a significant shortfall.
Avoid this by:
- Including inflation in retirement calculations.
- Reviewing your retirement corpus periodically.
- Increasing investments as income grows.
3. Depending Only on EPF or Pension
Employees often assume that EPF, gratuity, or pension will be enough.
Unfortunately, these sources alone rarely provide sufficient income for a comfortable retirement.
Medical expenses, lifestyle changes, travel, and longevity require additional financial resources.
Retirement should ideally have multiple income sources such as:
- Mutual Funds
- National Pension System (NPS)
- Equity Investments
- Fixed Income Products
- Rental Income
- SWP from Mutual Funds
Diversification provides stability and flexibility.
4. Ignoring Healthcare Costs
Healthcare inflation is generally much higher than normal inflation.
As people age, medical expenses increase significantly due to:
- Regular health checkups
- Medicines
- Hospitalization
- Long-term care
- Critical illnesses
Without adequate health insurance, retirement savings can disappear quickly.
Remember:
Health insurance is an essential part of retirement planning—not an optional expense.
5. Not Having a Retirement Goal
Many people simply invest without knowing how much they actually need.
Questions you should answer include:
- At what age do you want to retire?
- What lifestyle do you expect?
- Where will you live?
- How much monthly income will you require?
- Will you travel frequently?
- Will you support your children financially?
Without clear goals, investment decisions become random.
A defined retirement target makes planning easier and measurable.
6. Withdrawing Retirement Investments Prematurely
Many investors withdraw long-term investments for:
- Buying a car
- Vacation
- Home renovation
- Children's short-term expenses
Every premature withdrawal reduces future wealth because compounding gets interrupted.
Your retirement investments should remain dedicated only to retirement.
Treat them as untouchable.
7. Investing Too Conservatively Throughout Life
Keeping all retirement savings in Fixed Deposits or Savings Accounts may feel safe but often fails to beat inflation.
Over long periods, equity has historically delivered better inflation-adjusted returns compared to traditional fixed-income products.
A balanced asset allocation based on your age and risk profile is usually more effective.
Example:
- Young investors can generally allocate a higher portion to equity.
- As retirement approaches, gradually shift towards debt and other stable assets.
8. Not Reviewing the Retirement Plan
Life changes.
Your retirement plan should change too.
Factors that affect retirement planning include:
- Salary increases
- Career changes
- Marriage
- Children
- Home purchase
- Inflation
- Market performance
Review your retirement portfolio at least once every year.
Adjust SIPs whenever your income increases.
9. Ignoring Tax Planning
Taxes can significantly reduce retirement income if not planned properly.
Understanding taxation on:
- Mutual Funds
- NPS withdrawals
- Pension income
- Fixed Deposits
- Capital gains
helps improve post-retirement cash flow.
A tax-efficient withdrawal strategy is just as important as wealth creation.
10. Depending Entirely on Children
Traditionally, many parents believed their children would financially support them after retirement.
Modern lifestyles have changed considerably.
Children may:
- Live abroad
- Have their own financial commitments
- Face career uncertainties
Financial independence during retirement preserves dignity and reduces pressure on family relationships.
Plan your retirement assuming you will be financially self-reliant.
11. Ignoring Emergency Funds
Unexpected expenses don't stop after retirement.
Without an emergency fund, retirees may have to sell long-term investments during unfavorable market conditions.
Maintain emergency savings equivalent to at least 6–12 months of expected expenses in highly liquid instruments.
12. Not Planning for Longer Life Expectancy
People are living longer than ever before.
Retirement may last 25 to 35 years.
Many people plan only until age 75 or 80, while they may live well into their 90s.
Your retirement corpus should support a long life with rising expenses.
Planning for longevity reduces the risk of outliving your savings.
Practical Tips for Better Retirement Planning
To build a secure retirement:
- Start investing as early as possible.
- Increase SIPs annually with salary hikes.
- Diversify across suitable asset classes.
- Maintain adequate health insurance.
- Review your retirement plan every year.
- Avoid unnecessary withdrawals.
- Consider inflation in every calculation.
- Build an emergency fund.
- Create multiple income sources.
- Consult a qualified personal finance professional whenever needed.
Conclusion
Retirement planning is not merely about accumulating a large corpus—it is about creating financial freedom for your later years. The mistakes discussed above are common, but they are entirely preventable with timely action, disciplined investing, and periodic reviews.
Remember, retirement planning is a marathon, not a sprint. Every SIP, every disciplined investment, and every informed financial decision today contributes to a more secure and stress-free tomorrow.
The best time to start planning for retirement was yesterday. The next best time is today.
A well-planned retirement ensures that your golden years are filled with comfort, independence, and the confidence to enjoy life on your own terms.